
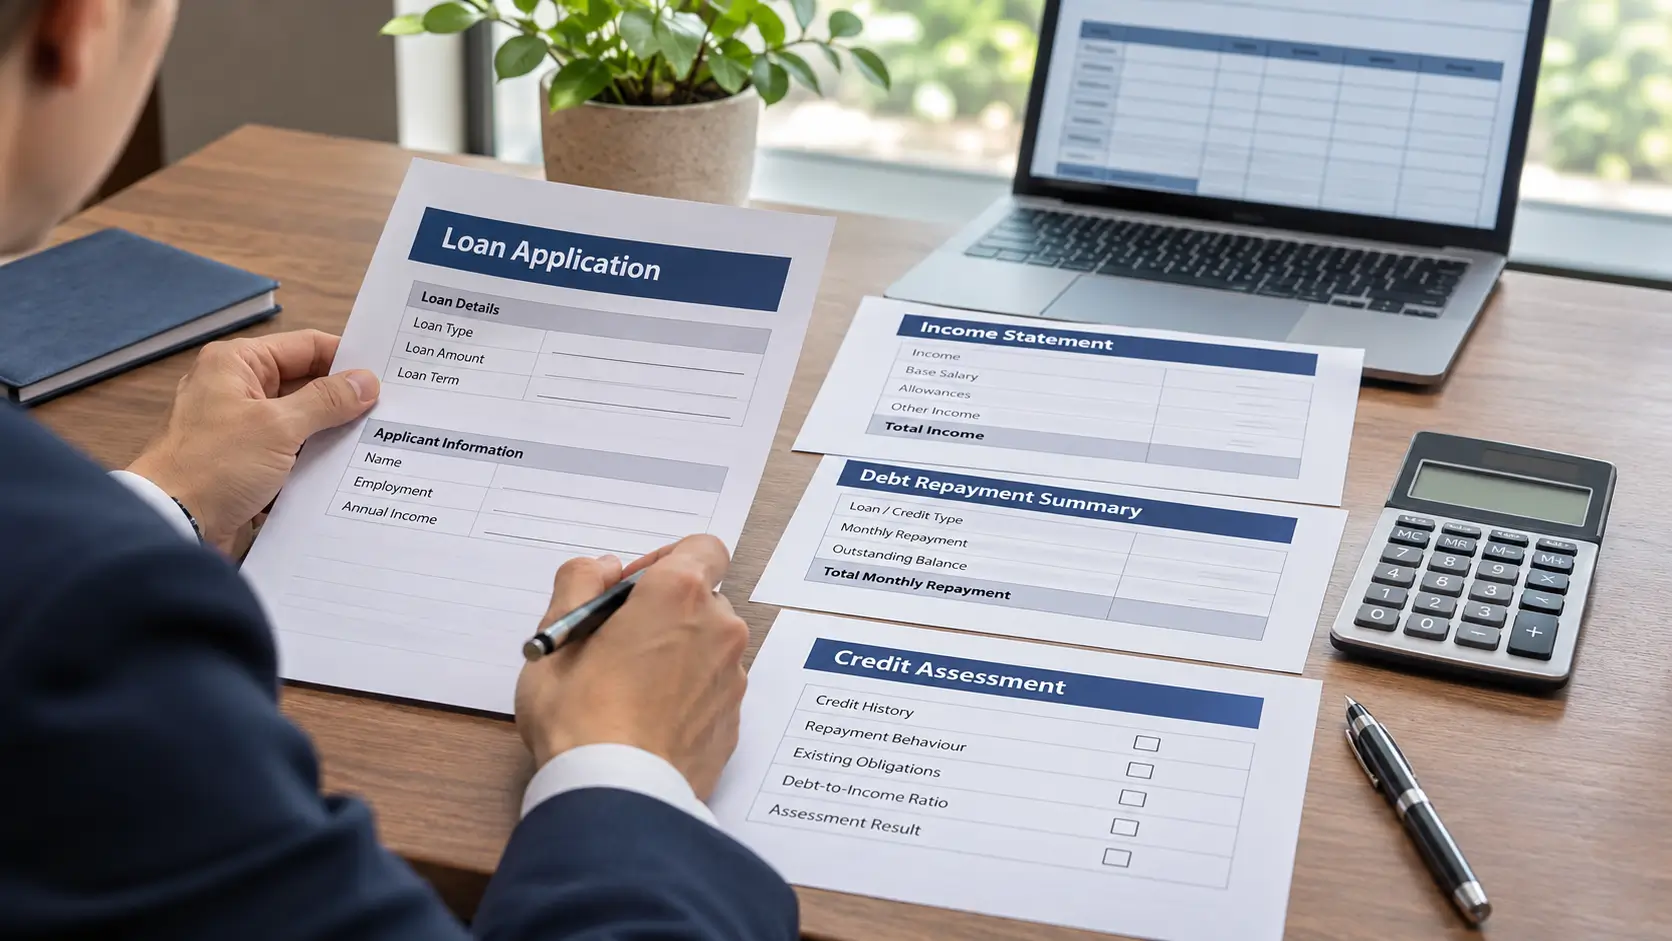
A higher income can improve a person's chances of qualifying for a bank loan and may support a larger loan amount. But earning more does not automatically mean a bank will approve an application or offer more credit. Lenders also examine existing debts, the reliability of income, credit history, the purpose of the loan, and any security offered.
Approval and affordability are different. A bank may offer a loan that leaves little room for essential expenses or unexpected income changes. Applicants need to assess both eligibility and repayment costs.
Does Higher Income Increase Loan Approval Chances?
Higher income generally strengthens an application when other circumstances are similar. Someone who earns more may have greater capacity to meet monthly repayments, especially if their existing debt payments are modest.
However, income alone cannot establish how much a person can safely borrow. A high earner with several outstanding loans may have less money available for new payments than a moderate earner with few debts. Unstable earnings or a history of missed payments can also affect the bank's decision.
No income level guarantees approval, and a larger salary does not automatically justify taking out multiple loans. Each new repayment adds to existing commitments. Requirements vary by lender, product, and country.
What Factors Determine Bank Loan Eligibility?
Banks assess several connected factors to estimate whether a borrower can repay the proposed loan under its terms. The importance of each factor depends on the product and the lender's policies.
Income Amount, Source, and Stability
Lenders need to understand both how much an applicant earns and how dependable those earnings are. A regular salary may be easier to document than variable earnings from freelance work, commissions, or a recently established business.
Banks may request payslips, bank statements, tax documents, or business records, depending on local rules and the loan.
Applicants with irregular income are not automatically ineligible. A lender may examine earnings over a longer period or ask for additional records. Applicants should check whether the bank assesses gross income, take-home pay, or business earnings.
Debt-to-Income Ratio
The debt-to-income ratio (DTI) compares monthly debt payments with gross monthly income. It helps a lender assess how much of a borrower's income is already committed to repayment.
The basic calculation is:
For example, a borrower earning 100,000 currency units per month before deductions and paying 25,000 toward existing debts has a DTI of 25%. If a proposed loan adds a monthly payment of 10,000, the combined payments would represent 35% of that income. This is an illustrative calculation, not a recommended or universally accepted lending limit.
Lenders may count different obligations and apply different thresholds. The Consumer Financial Protection Bureau's explanation of debt-to-income ratio describes the calculation and notes that limits vary by loan and lender. Applicants should confirm how their own bank calculates affordability.
Credit History and Credit Scores
Credit history records how a borrower has managed previous credit obligations. Where credit scoring systems are used, a score summarizes information from a credit report to help estimate repayment risk.
A stronger credit record may support approval or more favorable terms, but it does not outweigh every other concern. Lenders can use different scoring models, and the score a borrower sees may differ from the one used for a particular application. Some markets and loan products rely more heavily on credit records or other assessments than on a single numerical score.
The Consumer Financial Protection Bureau's guide to understanding credit scores explains the factors behind scores and why they can differ. Where credit reports are available, applicants can check for errors and keep payments on schedule.
Employment, Assets, and Collateral
Employment history and other dependable income sources can provide evidence of repayment capacity. Savings and other assets can also matter.
Collateral is an asset pledged to secure a loan, such as a home or vehicle. It can reduce the lender's potential loss if the borrower defaults, but it does not remove the need to assess repayment ability. If the borrower fails to meet the agreement, the pledged asset may be at risk.
For property loans, the bank may also compare the amount borrowed with the property's assessed value and consider the applicant's down payment.
Loan Purpose and Lender Requirements
A housing loan, personal loan, and business loan do not follow identical approval criteria. Banks examine the purpose of the borrowing, repayment period, supporting documents, and any product-specific conditions.
Business lenders consider cash flow; housing lenders assess property information. Different bank policies can produce different decisions on the same application.
Does More Income Mean a Larger Loan or Lower Interest Rate?
Higher verified income may support a larger loan because it can increase the amount available for repayments. The amount also depends on debts, loan term, collateral, and lender policy.
A lower interest rate is not guaranteed either. Rates can reflect credit risk, loan type, security, repayment term, and market conditions. A higher earner with substantial debt or weaker credit history may receive less favorable terms.
Applicants should distinguish the interest rate from the total borrowing cost. Where annual percentage rate (APR) is disclosed, it generally reflects interest plus certain loan charges. Fees, repayment schedules, and early repayment conditions also deserve attention. A longer term may reduce monthly payments while increasing the total interest paid.
Which Loans Can Higher Earners Apply For?
Higher earners may qualify for larger amounts under ordinary loan products, rather than needing a special category of loan. Eligibility depends on the loan's purpose and the lender's assessment.
Personal Loans
Personal loans can be used for permitted personal expenses, subject to the lender's terms. Some are unsecured, meaning no specific asset is pledged as collateral. Others require security.
Income, debt commitments, and creditworthiness affect approval. Unsecured loans may carry higher rates than comparable secured loans because the lender has no pledged asset to recover.
Home Loans and Jumbo Mortgages
Housing lenders consider income alongside existing debts, down payment, property value, and credit history. A larger salary can support a higher repayment amount, but a larger mortgage also creates a longer financial obligation.
In the United States, a jumbo mortgage generally means a mortgage above the applicable conforming-loan limit. It is not simply a special loan for people with high incomes. Pricing, documentation, and down-payment requirements differ by lender; jumbo loans do not invariably have higher rates.
The term and its associated limits are specific to the US mortgage market. Other countries use different housing-loan classifications.
Business Loans
Business loans fund eligible business activities, such as operations or expansion. A business owner's personal income may matter, but lenders also examine the business's financial performance, cash flow, liabilities, and ability to service debt.
For example, the US Small Business Administration identifies creditworthiness and reasonable ability to repay among eligibility considerations for its 7(a) program. This illustrates why a high personal salary alone does not establish business-loan eligibility.
What Are the Benefits and Risks of Borrowing More?
Additional borrowing can provide access to funds for a planned expense, property purchase, or business need. The benefit depends on the purpose and whether the cost of credit is manageable.
Possible benefits include spreading the cost of a substantial purchase over time, preserving some savings for necessary expenses, and funding an activity that has a realistic financial purpose. When a lender reports repayment activity to credit bureaus, consistent on-time payments may also contribute to a positive credit record. This effect is not available for every loan or scoring system.
The risks increase when repayments take up too much of the borrower's available income:
-
Interest and fees increase the total cost of the purchase.
-
Variable-rate loans may become more expensive if rates rise.
-
Additional debt reduces flexibility when income falls or expenses increase.
-
Missed payments may lead to charges, collection activity, or harm to credit history.
-
Default on a secured loan may put the pledged property at risk.
Investments financed by loans carry uncertainty: returns are not assured, but repayments remain due. Tax deductions, if any, depend on the jurisdiction, the loan's use, and applicable rules; they should not be assumed.
How Can Borrowers Improve Loan Eligibility?
Improving eligibility involves making repayment capacity easier to demonstrate and reducing avoidable risks. Several steps may help, although none guarantees approval.
-
Review existing debts: Reducing outstanding balances or monthly commitments may improve affordability and DTI.
-
Check credit records: Where available, review reports for errors, correct inaccurate entries, and keep payments on schedule.
-
Document income accurately: Prepare the salary, bank, tax, or business records needed to show consistent earnings.
-
Apply for a realistic amount: A smaller loan may be easier to manage than the maximum offered by a lender.
-
Compare loan terms: Examine repayment amounts, fees, interest-rate conditions, and the total amount due, not only the advertised rate.
-
Consider a co-signer cautiously: Where permitted, a qualified co-signer may help an application, but that person becomes responsible for repayment if the borrower cannot pay. Both parties should understand the obligation before agreeing.
Only genuine, verifiable income increases can support a reassessment; approval is still not assured.
How Much Borrowing Is Financially Manageable?
A bank's approval limit is not a personal spending target. Borrowers should test the proposed payment against their actual budget, including costs that may not be reflected fully in the lender's DTI calculation.
Begin with dependable take-home income. Subtract housing, food, transport, utilities, family commitments, existing repayments, and other necessary expenses. Then consider irregular costs and whether enough money would remain if income temporarily declined.
Before accepting an offer, check the repayment term, total interest and fees, penalties, collateral conditions, and whether the payment can change. A comparison of written offers is more useful than relying on the largest amount a lender is willing to approve.
Readers who want a broader starting point for budgeting and evaluating borrowing costs can consult Collegenp's personal finance education guide.
Conclusion
Higher income can improve bank loan eligibility and support a larger loan, but it is only one part of the decision. Credit history, debt obligations, income stability, loan purpose, and collateral can all change the outcome.
The more useful question is not how much a bank will lend, but whether the repayments and total borrowing cost remain manageable. Loan terms and consumer protections differ by country, so applicants should check the applicable requirements with a regulated lender. This article provides general financial education, not individualized financial advice.
Comments 0
No comments yet. Be the first to start the conversation.