
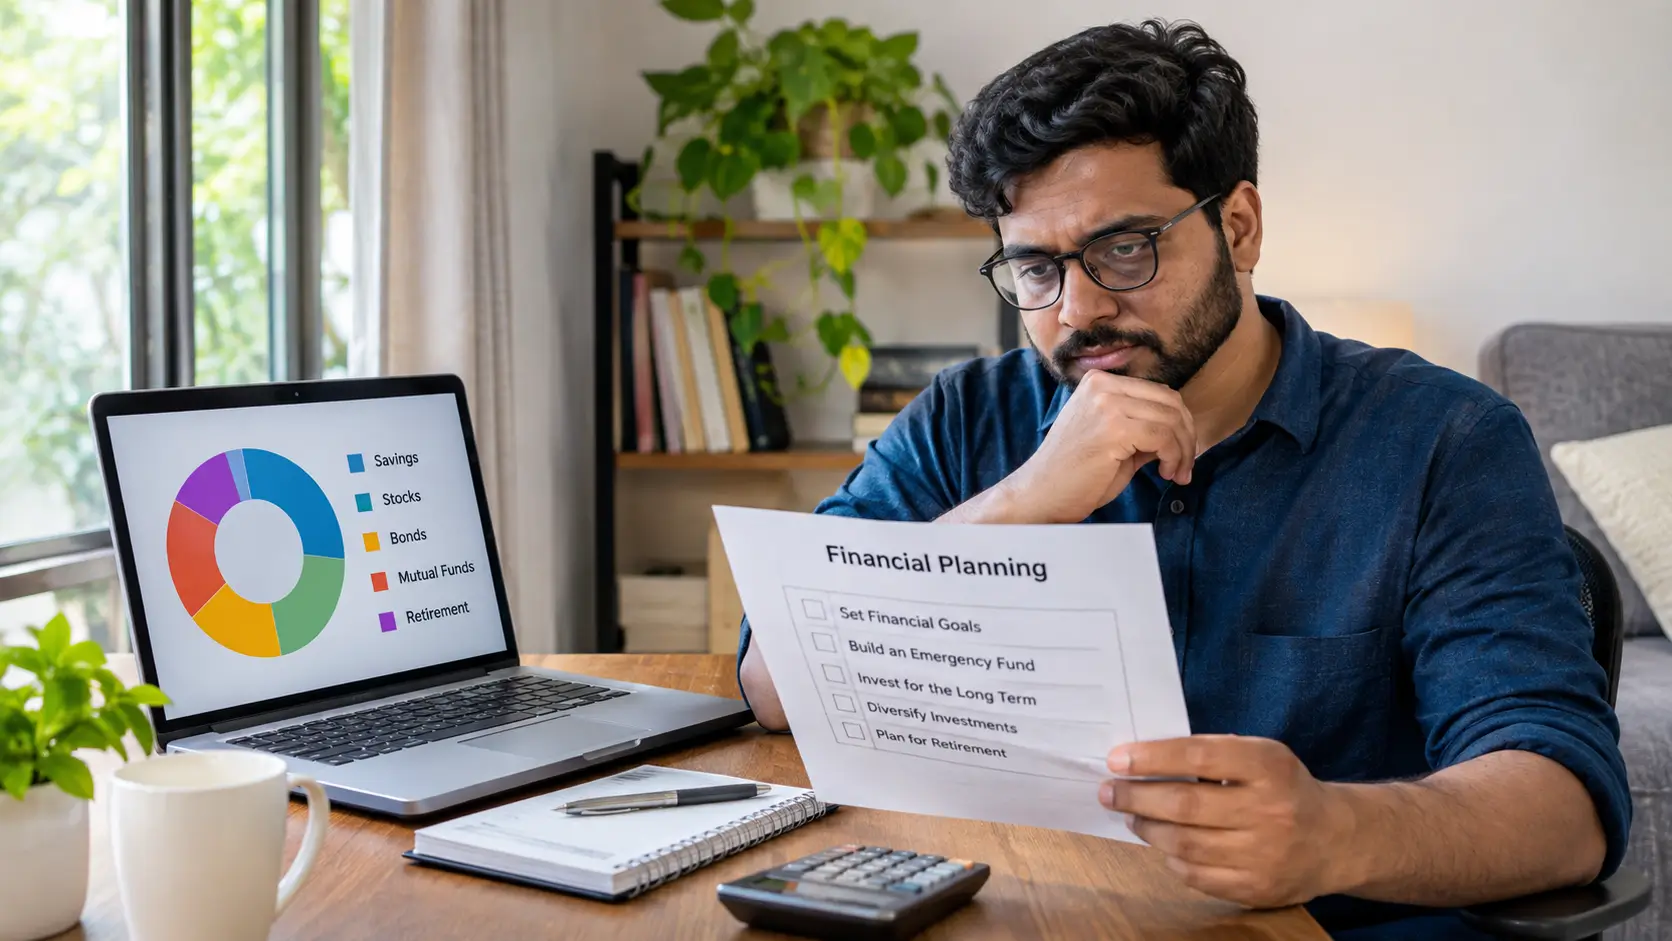
Investing involves putting money into assets with the expectation of earning income or benefiting from an increase in value. It can support long-term financial goals, including education, home ownership, and retirement. However, investment returns are uncertain, and some assets can lose a substantial portion of their value.
For beginners, the challenge is understanding the difference between saving and investing, comparing available financial products, and deciding how much risk is appropriate for a particular goal.
Stocks, bonds, mutual funds, exchange-traded funds (ETFs), and real estate offer different opportunities and limitations. Savings accounts and fixed deposits serve a different purpose: they generally prioritize preserving money and earning interest rather than pursuing substantial investment growth.
Before committing funds, it is necessary to understand the investment's underlying assets, costs, liquidity, and potential losses.
This guide explains ten ways to save or invest money, the risks involved, and the basic principles of building a long-term financial plan.
Answer Summary: Beginners can consider interest-bearing savings accounts, fixed deposits, government bonds, corporate bonds, stocks, mutual funds, ETFs, real estate investment trusts, direct property ownership, and commodities. These options differ in risk, accessibility, income potential, and liquidity. A suitable financial plan depends on when the money will be needed, the investor's ability to absorb losses, applicable fees and taxes, and the availability of regulated products.
Key Takeaways:
-
Investing offers the possibility of returns but involves financial risk.
-
Savings products and investments serve different financial purposes.
-
Higher potential returns generally involve greater uncertainty or risk.
-
Diversification can reduce concentration risk but cannot prevent all losses.
-
Investment fees, inflation, and taxes affect actual returns.
-
Retirement planning requires attention to time horizons and withdrawal rules.
-
Investment decisions should reflect personal financial circumstances rather than advertised earnings.
What Is Investing, and How Does It Work?
Investing means allocating money to assets with the expectation of receiving a financial return over time.
According to the U.S. Securities and Exchange Commission's investor education website, Investor.gov, investment returns may come from an increase in an asset's value or from payments such as interest and dividends.
For example, an investor who owns shares in a company may benefit if the market value of those shares increases. A bondholder may receive interest payments under the bond's terms, provided the issuer meets its obligations.
Investment income and capital appreciation are not interchangeable.
-
Capital appreciation: An increase in an asset's market value.
-
Interest income: Payments associated with lending money or certain deposit arrangements.
-
Dividend income: Distributions made by a company or investment fund to eligible investors.
-
Capital loss: A decrease in value that results in a loss when an asset is sold, or when its value otherwise becomes unrecoverable.
An investment's value can change because of economic conditions, interest rates, business performance, market demand, or other factors.
How Does Compound Growth Work?
Compound growth occurs when returns remain invested and subsequent returns are earned on both the original investment and previously accumulated returns.
For a savings product that pays compound interest, interest is added to the balance according to the account's terms.
For market investments, growth can also compound when returns are reinvested, but negative returns and market fluctuations can interrupt or reverse that growth.
Compounding is influenced by time, contributions, returns, fees, and withdrawals. It is a mathematical effect, not a guarantee that an investment will increase in value.
Saving vs. Investing: What Is the Difference?
Saving generally focuses on preserving money for planned or unexpected expenses. Investing involves accepting financial risk in pursuit of potential income or capital growth.
| Factor | Saving | Investing |
|---|---|---|
| Main purpose | Preserve accessible funds | Seek financial returns |
| Common products | Savings accounts, fixed deposits | Stocks, bonds, funds, property |
| Risk | Generally lower for eligible insured deposits | Depends on the asset |
| Return | Usually interest-based | Income, appreciation, or both |
| Accessibility | Depends on account conditions | Depends on investment liquidity |
| Main limitation | Inflation may reduce purchasing power | Market losses are possible |
The distinction matters because money needed for an upcoming expense may not be suitable for an investment that can fall sharply in value.
What Should Beginners Consider Before Investing?
The first investment decision is not which product to purchase. It is determining how much money can be committed without compromising necessary expenses or financial stability.
Build an Emergency Savings Reserve
An emergency fund is money set aside for unexpected expenses, such as urgent repairs, medical bills, or a temporary loss of income.
The U.S. Consumer Financial Protection Bureau explains that emergency savings can help households manage financial shocks without relying entirely on borrowing.
The appropriate amount depends on individual expenses, income stability, and personal circumstances.
Emergency money generally needs to remain accessible rather than being exposed to substantial market fluctuations.
Review Existing Financial Obligations
Existing debts, recurring payments, and essential living expenses affect the amount available for investing.
Debt carrying high interest charges can create a financial burden that outweighs uncertain investment gains.
Comparing borrowing costs with potential investment returns can help clarify priorities, although individual circumstances may require professional guidance.
Define Financial Goals
Financial goals determine when money will be needed and how much uncertainty is manageable.
A goal expected within a relatively short period usually has a different risk profile from retirement savings intended for use decades later.
Investor.gov emphasizes that investment time horizons and risk tolerance are central to asset allocation decisions.
Understand Your Risk Tolerance
Risk tolerance refers to an investor's willingness and ability to accept financial losses.
Someone may be emotionally comfortable with market fluctuations but unable to absorb a large loss without affecting essential expenses.
Both financial capacity and personal comfort matter when evaluating risk.
10 Ways to Save and Invest Money
These ten options range from conventional savings products to market investments and physical assets. They are not ranked by returns or suitability, and they are not all available under the same conditions in every country.
1. Interest-Bearing Savings Accounts
An interest-bearing savings account allows money to be deposited with a financial institution while earning interest under the account's terms.
Some accounts offer higher interest rates than standard savings products. The term "high-yield savings account" is commonly used in certain markets, including the United States.
Potential Benefits
Savings accounts may provide straightforward access to funds and relatively predictable interest arrangements.
Eligible deposits may also receive protection under a country's deposit insurance or guarantee system, subject to the relevant institution, product, and coverage limits.
Risks and Limitations
Interest rates may change, and account conditions can include fees or withdrawal restrictions.
Inflation may also exceed the interest earned, reducing the purchasing power of the balance.
In the United States, the Federal Deposit Insurance Corporation (FDIC) provides deposit insurance for eligible deposits at insured banks, subject to coverage rules. This protection does not extend to stocks, mutual funds, or bonds.
Deposit protection outside the United States follows the applicable national system.
Savings accounts may suit money that needs to remain accessible, but they should not be confused with investments designed for substantial capital growth.
2. Fixed Deposits and Certificates of Deposit
Fixed deposits, also known as term deposits in some countries, generally involve placing money with a financial institution for an agreed period.
Certificates of deposit (CDs) are a related deposit product commonly offered in the United States.
Potential Benefits
These arrangements may offer a stated interest rate for a defined term, making the contractual interest payments easier to anticipate.
They can be useful for funds that are not needed immediately, provided the maturity date matches the saver's plans.
Risks and Limitations
Early withdrawal may lead to penalties, reduced interest, or restrictions.
The purchasing power of the deposit can decline if inflation exceeds the effective return.
Deposit insurance eligibility and limits depend on the country, institution, and account conditions.
Before selecting a fixed deposit, compare maturity terms, interest calculations, fees, renewal conditions, and withdrawal restrictions.
3. Government Bonds and Treasury Securities
Government bonds are debt instruments issued by public authorities to raise funds.
Investors effectively lend money to the issuer under specified repayment conditions.
Government securities may include Treasury bills, notes, and bonds, although product structures differ by country.
Potential Benefits
Some government securities provide defined interest payments, while others are issued at a discount and repay a stated amount at maturity.
Securities issued by financially strong governments are often regarded as having relatively low default risk in their own currencies.
Risks and Limitations
Government bonds are not universally risk-free.
Their market prices can fluctuate when interest rates change. Investors who sell before maturity may receive more or less than the purchase price.
Inflation, currency movements, and sovereign credit conditions can also affect returns.
Before investing, examine the issuing authority, maturity date, payment terms, currency, and whether the security is intended to be held until maturity.
4. Corporate Bonds
Corporate bonds are debt securities issued by companies to raise money for business activities.
Bondholders generally have contractual rights to interest and repayment, subject to the issuer's financial ability and the bond's terms.
Potential Benefits
Corporate bonds can provide a defined income structure and exposure to a different type of financial asset from company shares.
They may also form part of a diversified fixed-income portfolio.
Risks and Limitations
The issuing company may fail to make scheduled payments or repay the principal.
Bond prices may fall when market interest rates increase or the issuer's creditworthiness deteriorates.
Some corporate bonds offer higher yields because investors face greater default risk.
Investor.gov explains that lower-rated, high-yield corporate bonds carry greater credit risk than investment-grade corporate bonds.
A higher advertised yield should be evaluated alongside the issuer's financial condition, credit risk, maturity, and other bond terms.
5. Individual Stocks
A stock represents an ownership interest in a company.
Stockholders may benefit from increases in share prices and, when declared, dividend distributions.
Potential Benefits
Stocks allow investors to participate in the financial performance of listed companies.
Over long historical periods, diversified equity investments in some major markets have generated substantial returns. However, this historical experience does not establish what individual companies or future markets will deliver.
Risks and Limitations
Stock prices can fluctuate considerably.
A company may face declining profits, increasing debt, competitive pressure, or business failure.
An investor who concentrates money in a small number of companies faces greater exposure to company-specific events.
Dividends are also uncertain and may be reduced or suspended.
For beginners, understanding company financial statements, business models, valuations, and market risk is more useful than relying on short-term price predictions.
Individual stocks can involve substantial losses, including the loss of the entire amount invested.
6. Mutual Funds
A mutual fund pools money from multiple investors and invests according to a stated objective.
Depending on its mandate, a fund may hold stocks, bonds, money-market instruments, or a combination of assets.
Some funds are actively managed, while others follow an index-based strategy.
Potential Benefits
Mutual funds can provide access to a professionally managed portfolio without requiring investors to select every underlying security individually.
A broadly diversified fund may reduce the impact of poor performance by a single holding.
Funds may also offer arrangements for regular contributions or reinvestment of distributions, depending on their rules.
Risks and Limitations
A mutual fund is not automatically diversified across all sectors or asset types.
A fund concentrated in one industry or market may experience substantial losses.
Investors also pay management and operating expenses. These charges reduce the returns retained by fund investors.
The SEC notes that mutual fund losses remain possible and that past performance does not predict future returns.
Before comparing funds, examine their objectives, holdings, fees, investment strategy, redemption conditions, and risk disclosures.
7. Exchange-Traded Funds and Index Investing
An exchange-traded fund (ETF) is an investment fund whose shares are traded on a securities exchange.
Many ETFs hold portfolios of stocks or bonds. Others follow narrower investment strategies.
An index fund seeks to track the performance of a specified market index. It can be structured as either a mutual fund or an ETF.
Potential Benefits
Some broad-market ETFs provide exposure to numerous securities through a single fund.
Index-based products may also involve lower management and trading expenses than certain actively managed alternatives.
ETF shares generally trade during market hours on exchanges where they are listed.
Risks and Limitations
ETF prices fluctuate with market conditions and may differ from the value of their underlying holdings.
Not all ETFs are broadly diversified. Some focus on a single industry, narrow investment theme, or individual asset.
Certain exchange-traded products also use complex structures or borrowing arrangements that introduce additional risks.
Index investing does not eliminate market risk. If the tracked index falls, an index fund may also lose value.
The SEC advises investors to review fund documentation, underlying holdings, investment strategies, and fees before investing.
8. Real Estate Investment Trusts
Real estate investment trusts (REITs) provide a way to invest in certain income-producing real estate assets without purchasing an entire property.
A REIT may own or finance commercial buildings, residential properties, warehouses, or other eligible real estate assets.
REIT structures and regulatory requirements vary by jurisdiction.
Potential Benefits
Publicly traded REITs can provide exposure to real estate through securities that trade on exchanges.
Some REITs distribute income derived from property-related operations.
They may offer an alternative to the substantial capital and management responsibilities associated with direct property ownership.
Risks and Limitations
REIT prices can decline because of property market conditions, borrowing costs, interest rates, or business performance.
Dividend payments are not assured.
Non-traded REITs may be difficult to sell and can involve significant fees and limited price transparency.
The U.S. Securities and Exchange Commission identifies liquidity and valuation concerns as important risks for non-traded REITs.
Investors should understand the specific REIT structure, assets, debt exposure, fees, and local availability.
9. Direct Real Estate Investment
Direct real estate investing involves purchasing property with the intention of earning rental income, benefiting from appreciation, or both.
Properties may include residential units, land, or commercial premises.
Potential Benefits
Property ownership provides direct exposure to a physical asset.
Rental income may help offset ownership expenses when a property is occupied and payments are received.
Property values may also appreciate over time, depending on market conditions.
Risks and Limitations
Direct ownership often requires substantial capital.
Expenses can include purchase taxes, registration charges, maintenance, repairs, insurance, financing costs, and property management.
Vacancies, unexpected repairs, tenant disputes, and changes in local property markets may reduce income.
Real estate is also relatively illiquid. Selling a property may require significant time and transaction expenses.
Borrowing to purchase property increases financial exposure because loan obligations remain even when rental income or property values decline.
Property ownership should not automatically be described as passive income, particularly when the owner is responsible for maintenance and tenant management.
10. Gold and Other Commodities
Commodities are physical resources or materials, including precious metals, energy products, and agricultural goods.
Individual investors may encounter commodities through physical ownership or investment products designed to provide exposure to commodity prices.
Potential Benefits
Certain commodities behave differently from stocks and bonds under particular economic conditions.
Gold, for example, is sometimes considered by investors concerned about currency conditions or financial uncertainty.
Risks and Limitations
Commodity prices can be volatile and may decline over extended periods.
Physical holdings may involve storage, insurance, verification, and transaction costs.
Gold does not independently generate interest or dividend income.
Products linked to commodities may also have structures and risks that differ from physical ownership.
Commodity exposure should not be assumed to protect against every inflationary period or market downturn.
What Are the Major Risks Associated With Investing?
Investment risk is the possibility that actual financial outcomes will differ from expectations, including the possibility of losing money.
Different products carry different combinations of risk.
Market Risk
Market risk arises when investment values decline because of changes in economic conditions, investor sentiment, company performance, or broader financial markets.
Stocks and market-based investment funds are exposed to this risk.
Inflation Risk
Inflation reduces the purchasing power of money over time.
If an investment earns a return below the rate of inflation, its value in purchasing-power terms may decline even when the nominal balance increases.
Interest Rate Risk
Changes in market interest rates affect the value of many fixed-income securities.
For example, an existing fixed-rate bond may lose market value when newly issued bonds offer higher interest rates.
Credit Risk
Credit risk is the possibility that a borrower or issuer will fail to meet payment obligations.
It is particularly relevant to corporate bonds and other debt instruments.
Liquidity Risk
Liquidity risk arises when an investment cannot be sold quickly at a reasonable price.
Direct property, certain bonds, and non-traded investment products can involve significant liquidity constraints.
Currency Risk
Investments denominated in a foreign currency may gain or lose value when exchange rates change.
Currency movements can affect the return received in an investor's home currency.
Fraud and Operational Risk
Fraudulent investment schemes, unauthorized intermediaries, custody problems, and operational failures may also create financial losses.
Regulatory oversight and transparency are important considerations, although regulation does not remove ordinary investment risk.
Investment Strategies for Beginners
Investment strategies describe how money is allocated, contributed, and managed over time.
The following approaches can help beginners evaluate investment decisions without relying on short-term predictions.
Dollar-Cost Averaging
Dollar-cost averaging involves investing a fixed amount at regular intervals regardless of market conditions.
When the investment price is lower, the same contribution purchases more units. When the price is higher, it purchases fewer.
This method establishes a consistent contribution pattern and reduces the need to choose a specific market entry date.
However, dollar-cost averaging does not guarantee profits, prevent losses, or ensure a better return than investing an available lump sum.
Buy-and-Hold Investing
A buy-and-hold strategy involves retaining investments over an extended period rather than frequently trading in response to short-term price movements.
This approach can reduce trading activity and its associated expenses.
It still requires periodic review, particularly when an investment's underlying circumstances or the investor's financial objectives change.
Holding an unsuitable or deteriorating investment for longer does not automatically make it safer.
Diversification
Diversification means spreading investments among different assets, companies, sectors, or markets to reduce dependence on a single source of return.
For example, a portfolio containing several unrelated investments may be less exposed to the failure of one company than a portfolio concentrated entirely in that company's shares.
Diversification does not eliminate broad market losses.
The SEC explains that diversification and asset allocation are related but distinct concepts.
Asset Allocation
Asset allocation refers to the proportion of a portfolio held in different asset classes, such as stocks, bonds, and cash.
The appropriate mix depends on investment objectives, time horizon, risk tolerance, and financial capacity.
An allocation suitable for a distant retirement goal may be inappropriate for money needed in the near future.
Portfolio Rebalancing
Rebalancing involves reviewing and adjusting portfolio holdings when their proportions move away from a chosen allocation.
Changes may be made through new contributions or transactions involving existing holdings.
Transaction costs, taxes, and changing financial circumstances should be considered before making adjustments.
Understanding Value Investing
Value investing is an approach that seeks securities considered inexpensive relative to an estimate of their underlying economic value.
It requires assessing company finances, profitability, debt, competitive conditions, and valuation assumptions.
A share price that has fallen sharply is not necessarily evidence that the stock is undervalued.
Value estimates are uncertain, and a seemingly inexpensive investment can continue to lose value.
Are High-Yield Investments Worth the Risk?
A high-yield investment offers or is expected to provide a relatively high level of income or return compared with certain alternatives.
The word "yield" generally refers to income relative to an investment's price or another defined measure. It should not be confused with total return, which also accounts for changes in market value.
For instance, a bond may display an elevated yield because its price has declined amid concerns about the issuer's ability to repay its debt.
Similarly, a security with a high stated dividend yield may still produce a negative overall return if its market price falls.
High yield does not necessarily mean high profitability.
The SEC warns that promises of unusually high investment returns with minimal or no risk are a common warning sign of investment fraud.
When assessing a high-yield opportunity, examine where the payments are expected to come from, whether they depend on borrowing, the issuer's financial condition, and the possibility of losing principal.
An advertised rate should not be treated as evidence that an investment is safe.
Retirement Planning and Long-Term Investing
Retirement planning involves estimating future financial needs and establishing a strategy for saving and investing over time.
A retirement plan may include savings, pensions, employer-sponsored arrangements, and investment accounts.
The structure depends heavily on national laws, employment conditions, and available financial products.
Why Does the Investment Time Horizon Matter?
A longer investment horizon provides more time to make contributions and potentially benefit from compound growth.
It may also allow an investor to remain invested through certain periods of market volatility.
However, a long time horizon does not eliminate the possibility of poor returns or permanent losses.
Retirement planning should also account for inflation, future spending needs, possible interruptions in income, and the timing of withdrawals.
Understanding Retirement Accounts
Retirement accounts and retirement plans are not necessarily investment products themselves. They are arrangements through which savings or investments may be held and administered.
In the United States, examples include:
-
401(k) plans offered through eligible employers.
-
Traditional individual retirement arrangements (IRAs).
-
Roth IRAs, which have different tax treatment.
The U.S. Internal Revenue Service explains that these arrangements are subject to eligibility conditions, contribution rules, and tax requirements.
Other countries maintain different retirement and pension systems.
In Nepal, for example, the Social Security Fund administers contributory social protection arrangements that include old-age security provisions for eligible participants.
These systems should not be treated as interchangeable. Their benefits, restrictions, and tax treatment depend on the applicable rules.
Review Retirement Arrangements Periodically
A retirement plan may need to change as income, employment, family circumstances, and financial obligations change.
Periodic review can help determine whether contributions remain affordable, investment risks are appropriate, and the expected retirement resources remain aligned with financial needs.
How to Evaluate an Investment Before Committing Money
An investment should be understood before funds are committed.
The following questions can help beginners identify important information and limitations.
1. What Does the Investment Actually Own?
Identify whether the product represents company ownership, a loan, an investment fund, physical property, or another form of asset.
Understanding the source of potential returns is essential.
2. What Could Cause a Financial Loss?
Assess the investment's exposure to market conditions, issuer failure, borrowing, inflation, and liquidity restrictions.
A clear explanation of risk is more useful than a return projection without supporting assumptions.
3. What Fees and Taxes Apply?
Relevant expenses may include transaction charges, management fees, custody fees, property-related costs, and taxes.
The SEC's investor education materials explain that investment fees reduce the amount available to generate future returns.
Tax treatment depends on the investor's circumstances and the relevant jurisdiction.
4. How Easily Can the Investment Be Sold?
An investment may not be suitable for a near-term expense if it cannot be sold without substantial delay or loss.
Examine withdrawal conditions, maturity requirements, market liquidity, and possible penalties.
5. Is the Provider Properly Authorized?
Confirm whether the financial intermediary or product is subject to applicable registration, licensing, or regulatory requirements.
Investors in Nepal can consult the Securities Board of Nepal (SEBON) for information concerning securities markets and regulated market participants.
In the United States, Investor.gov provides information about checking investment professionals and identifying possible fraud.
Registration or licensing does not guarantee an investment return, but it is an important part of assessing legitimacy.
Conclusion
Investing can support long-term financial goals, but the available products differ substantially in how they generate returns and expose money to risk.
Savings accounts and fixed deposits generally emphasize capital preservation and contractual interest. Bonds provide debt-based investment exposure, while stocks and investment funds involve market risk. Real estate, REITs, and commodities introduce different costs, liquidity conditions, and sources of uncertainty.
There is no investment product that is appropriate for every person or financial goal.
For beginners, understanding financial obligations, setting realistic objectives, comparing costs, assessing risk tolerance, and reviewing reliable information are more important than pursuing the highest advertised return.
A sound investment decision begins with knowing what is being purchased, how its value may change, and what happens if the expected outcome does not occur.
Referemces
-
U.S. Securities and Exchange Commission, Investor.gov. Introduction to Investing. Explanation of investment returns, compound growth, and financial risk.
-
U.S. Securities and Exchange Commission, Investor.gov. Asset Allocation and Diversification. Guidance on investment time horizons, asset allocation, and diversification.
-
U.S. Securities and Exchange Commission, Investor.gov. Learn About Investment Options. Background information on major investment products and their risks.
-
U.S. Securities and Exchange Commission, Investor.gov. Bonds – FAQs. Explanation of bond structures, interest rate risk, credit risk, and other bond-related considerations.
-
U.S. Securities and Exchange Commission, Investor.gov. Mutual Funds. Guidance on pooled investments, fund objectives, expenses, and potential losses
-
U.S. Securities and Exchange Commission, Investor.gov. Exchange-Traded Funds (ETFs). Explanation of ETF structures, trading, diversification, and risks.
-
U.S. Securities and Exchange Commission, Investor.gov. Index Funds. Explanation of index-based investing and associated expenses.
-
U.S. Securities and Exchange Commission, Investor.gov. Real Estate Investment Trusts (REITs). December 2011. Explanation of REIT structures, liquidity, and investment risks.
-
U.S. Securities and Exchange Commission, Investor.gov. How Fees and Expenses Affect Your Investment Portfolio. July 2025. Guidance on the long-term effects of investment costs.
-
U.S. Securities and Exchange Commission, Investor.gov. Protect Your Money: How to Avoid Investment Scams. Guidance on investment fraud warning signs.
-
Consumer Financial Protection Bureau. An Essential Guide to Building an Emergency Fund. Guidance on accessible emergency savings and managing unexpected financial expenses.
-
Federal Deposit Insurance Corporation. Deposit Insurance. Explanation of eligible insured deposits and products not covered by U.S. deposit insurance.
-
Internal Revenue Service. 401(k) Plans. Official information about U.S. employer-sponsored retirement arrangements.
-
Securities Board of Nepal. Investor Education. Official educational information about securities and financial market participation in Nepal.
-
Social Security Fund, Nepal. Services. Official information about contributory social protection and old-age security arrangements.
Disclaimer: This article is intended for general financial education. It does not provide personalized investment, tax, or legal advice. Investment products, eligibility requirements, regulatory protections, and tax rules vary by jurisdiction. Financial losses are possible, and readers should verify current information with the appropriate regulator or qualified professional before making financial decisions.
Comments 0
No comments yet. Be the first to start the conversation.