
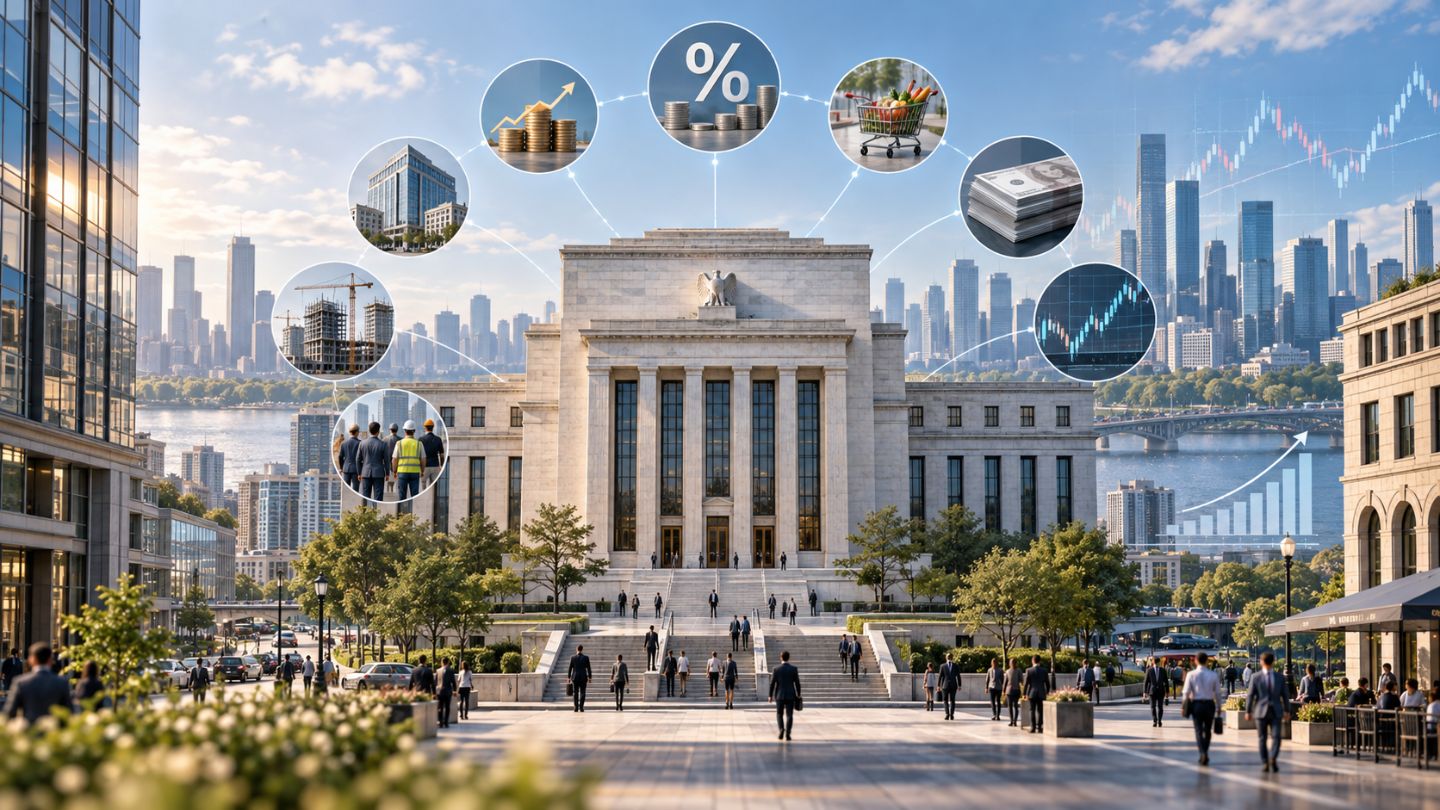
A central bank influences inflation, borrowing costs, access to credit, financial-system stability, and, in many countries, employment and economic activity. Its decisions can affect loan rates, bank funding, exchange rates, asset prices, and the willingness of households and firms to spend or invest.
A central bank does not control the economy by itself. Governments set taxes and public spending, businesses decide whether to invest and hire, and global events can change trade conditions and capital flows. Monetary policy works through this wider system with delays and uncertain effects.
Central-bank mandates also differ. The U.S. Federal Reserve has statutory goals that include maximum employment and stable prices, while the European Central Bank's primary objective is price stability. The Bank of England also has a price-stability objective and supports broader economic policy subject to its mandate.
What Is a Central Bank?
A central bank is the public monetary authority responsible for managing monetary conditions in a country or currency area. It usually sits at the center of the banking system and carries responsibilities that commercial banks do not have.
Depending on the legal framework, a central bank may set or guide short-term policy interest rates, conduct monetary operations, provide reserves to banks, issue currency, supply emergency liquidity, supervise financial institutions, oversee payment systems, manage foreign-exchange reserves, and monitor risks to financial stability.
The exact mix differs across jurisdictions. The Federal Reserve, for example, lists monetary policy, financial stability, supervision, payment-system functions, and consumer and community responsibilities among its main functions.
A commercial bank accepts deposits, makes loans, and serves households and businesses. A central bank operates at the system level, influencing monetary and financial conditions and often acting as a bank for commercial banks and the government.
What Are the Main Objectives of a Central Bank?
Price stability is a common central-bank objective, but other goals depend on the institution's legal mandate.
Price stability does not mean that every individual price stays unchanged. It means keeping overall inflation low and stable enough that households and businesses can make decisions without persistent changes in the general price level distorting those decisions.
Some central banks also have an explicit employment or output objective. The Federal Reserve is directed to promote maximum employment and stable prices. The ECB has a different hierarchy: maintaining price stability is its primary objective, while it supports the European Union's broader economic policies without prejudice to that objective.
Financial stability is another major responsibility in many systems. In some countries, the central bank is also a banking supervisor or macroprudential authority; in others, those duties are shared with separate regulators.
How Does Monetary Policy Work?
Monetary policy changes financial conditions in ways that influence spending, saving, investment, credit, and inflation. The process is often called the monetary-policy transmission mechanism.
A typical sequence begins when the central bank changes its policy rate or the terms on which banks can obtain or place funds. Money-market rates respond, followed by changes in bank lending rates, deposit rates, bond yields, and other financial prices. Households and firms then adjust some borrowing, saving, spending, and investment decisions. Those changes influence production, employment, and inflation over time.
The process is neither instant nor mechanical. The Federal Reserve notes that monetary policy affects economic activity, employment, and prices with a lag.
For related background, see Collegenp's article on how interest rates impact economic growth.
Policy Interest Rates
The policy interest rate is the most familiar monetary-policy tool. When policy rates rise, loans and market financing often become more expensive. Some households reduce interest-sensitive purchases, firms may delay investment, and demand can weaken. This tends to reduce inflation pressure over time.
When policy rates fall, financing conditions generally become easier. Borrowing and investment may increase, and lower debt-servicing costs can support spending. A rate cut does not guarantee stronger lending or growth, since banks may remain cautious and borrowers may not want new debt.
Open-Market and Liquidity Operations
Central banks also conduct transactions with financial institutions or in securities markets to keep short-term rates near the desired policy stance and ensure that the payment system has enough liquidity to function.
Traditional open-market operations involve buying or selling eligible securities or using repurchase transactions. The exact framework differs by central bank, but these operations help transmit the chosen policy stance to money-market rates.
Reserve Requirements
Some central banks require banks to hold minimum reserves against certain liabilities. Changing those requirements can affect bank liquidity and lending capacity.
Reserve requirements are not the main active policy tool in every system. Many central banks rely more on policy rates, standing facilities, and market operations. The ECB, for example, uses minimum reserves as part of its operational framework.
Balance-Sheet Policies and Forward Guidance
When short-term rates are near their effective lower bound or markets are under severe strain, a central bank may use other measures. These can include large-scale asset purchases, targeted lending facilities, or communication about the likely future path of policy.
Asset purchases aim to influence longer-term interest rates and broader financial conditions. Forward guidance seeks to shape expectations about future policy. Both depend on judgment about timing, scale, and market effects.
How Do Central Banks Affect Inflation?
Central banks influence inflation mainly by changing demand and financial conditions. They do not directly set the prices charged for food, fuel, housing, or other goods and services.
If inflation is being sustained by demand that is growing faster than the economy's capacity to supply goods and services, tighter monetary policy can reduce spending pressure. Higher interest rates can also affect inflation expectations, which matter for wage-setting and price-setting decisions.
Monetary policy has limits. It cannot produce more oil, repair a disrupted supply chain, improve a failed harvest, or remove a trade bottleneck. When inflation comes from supply shocks, policymakers face a harder task: prevent a temporary price shock from becoming persistent without weakening activity more than needed.
For a separate explanation of price pressures, see Inflation Causes and Its Impact on the Economy.
How Do Central Banks Affect Economic Growth and Employment?
Central banks influence growth and employment mainly through demand, credit conditions, and confidence in price stability. They do not create long-term growth on their own.
Lower interest rates can support borrowing, investment, housing activity, and household spending. If businesses face stronger demand, they may increase production and hiring. Higher interest rates tend to restrain demand.
A policy trade-off can arise when inflation is high. Tighter policy may slow spending and hiring while reducing inflation pressure. Excessive tightening, however, can weaken activity more than needed.
Long-run growth depends heavily on factors outside monetary policy, including productivity, education, infrastructure, labor-force growth, technology, competition, institutions, and fiscal policy. A central bank can support a stable monetary environment, but it cannot substitute for those foundations.
How Do Central Banks Influence Exchange Rates?
Monetary policy can affect exchange rates because interest-rate differences influence international investment decisions. Higher domestic rates may increase demand for domestic financial assets, while lower rates can have the opposite effect.
Interest rates are only one influence. Trade balances, political and financial risk, commodity prices, investor expectations, and actions by other central banks also matter.
Exchange-rate movements feed back into the economy. A weaker currency raises the domestic cost of imports and can add to inflation, while a stronger currency can reduce import costs. Export competitiveness can move in the opposite direction. The importance of these effects depends on how open the economy is and which exchange-rate regime it uses.
What Role Do Central Banks Play in Financial Stability?
Central banks can reduce the risk that stress in banks or financial markets disrupts payments, credit, and the broader economy. Their role is especially important when solvent institutions face temporary liquidity shortages or when key funding markets stop functioning normally.
One traditional function is lender of last resort: supplying liquidity to eligible financial institutions against appropriate collateral when private funding becomes unavailable. The Bank of England describes this role as liquidity provision to solvent but temporarily illiquid financial firms.
Financial stability also involves prevention. Central banks or partner regulators may use bank supervision, stress testing, capital and liquidity rules, and macroprudential measures. The IMF notes that macroprudential tools are designed to build buffers and limit vulnerabilities that can turn shocks into system-wide disruptions.
Monetary policy and financial-stability policy are related but not identical. An interest-rate decision aimed at inflation affects the whole economy, while a liquidity or prudential measure may target a specific source of stress.
What Did Central Banks Do During the 2008 Financial Crisis?
The 2007-2009 global financial crisis shows how central banks can use conventional and emergency tools when normal market functioning breaks down.
In the United States, the Federal Reserve cut its policy rate sharply as economic conditions weakened. It also expanded liquidity support, created emergency lending facilities, and later purchased longer-term securities to reduce borrowing costs and support credit conditions. Federal Reserve historical accounts describe this shift from rate cuts and discount-window changes to new liquidity programs and large-scale asset purchases.
The ECB also adjusted its liquidity operations during the financial turmoil to keep short-term money-market rates aligned with its policy stance and to help banks obtain funding through its operating framework.
These actions did not eliminate the recession or all financial losses. Their purpose was to keep monetary and financial channels functioning, reduce severe funding stress, and limit the feedback between financial disruption and falling economic activity.
The episode also shows why central-bank action is only one part of crisis management. Governments, deposit-insurance systems, bank-resolution authorities, fiscal agencies, and regulators can have separate roles.
Monetary Policy Is Not the Same as Fiscal Policy
Monetary policy is conducted by a central bank; fiscal policy is set by the government through taxation, public spending, borrowing, and budget decisions.
The distinction matters because the two policies work through different channels. A central bank can change interest rates and liquidity conditions, but it cannot decide how much a government spends on schools, roads, health services, transfers, or public investment. A finance ministry can change taxes and spending, but it does not normally set the central bank's policy rate.
The two can act in the same direction or in opposite directions. During a downturn, easier monetary policy and expansionary fiscal policy may both support demand. During high inflation, tighter monetary policy may conflict with fiscal measures that add strong demand.
For a focused comparison, see Difference Between Fiscal and Monetary Policy.
Why Does Central Bank Independence Matter?
Central-bank independence gives monetary policymakers room to make decisions under their legal mandate rather than short-term political pressure. Independence does not place a central bank above the law or remove accountability.
Governments or legislatures generally establish the mandate, governance structure, reporting duties, and appointment process. The central bank then receives some degree of operational freedom to pursue those goals.
IMF research and policy literature associate stronger central-bank independence with better inflation performance, while also stressing transparency and accountability.
Public statements, reports, meeting records, testimony, and forecasts help explain why decisions were made and what risks policymakers are considering.
What Are the Limits of Central Bank Power?
Central banks have strong tools, but their influence has clear boundaries.
Policy works with delays, and the transmission mechanism can weaken when banks restrict credit or borrowers are reluctant to take on debt. Central banks also cannot solve structural problems such as weak productivity, poor infrastructure, labor shortages, or supply disruptions.
Policy can involve trade-offs. Rapid rate increases may reduce inflation pressure but also slow investment and employment. Prolonged low rates can support demand while encouraging greater debt or risk-taking in some settings.
National policy is also affected by global conditions. Capital flows, commodity prices, foreign interest rates, exchange rates, and international financial shocks can complicate domestic decisions, especially in small or open economies.
These limits are why monetary policy works within a wider institutional framework that includes fiscal policy, financial regulation, public institutions, and policies that support productive capacity.
Long-Term Challenges for Central Banks
Central banks must adjust their methods as financial systems change while keeping their objectives clear.
Digital payments and new forms of money raise questions about payment-system design, bank funding, privacy, operational resilience, and the possible role of central bank digital currencies. The growth of nonbank finance also matters because credit and liquidity risks can emerge outside traditional banks.
Cross-border finance adds another challenge because shocks can move through exchange rates, funding markets, and investor behavior. Economic data also arrive with delays and are revised.
Sound policy depends on clear objectives, reliable evidence, risk assessment, transparent communication, and a willingness to change course when the evidence changes.
Final Perspective
A central bank has a major influence on national economic conditions because it shapes interest rates, liquidity, credit conditions, inflation expectations, and parts of the financial system. Its policies can support price stability and help stabilize economic activity, but their effects are indirect, delayed, and constrained by the structure of the economy.
The clearest way to understand central-bank policy is not to treat it as a single control switch for growth or inflation. Monetary decisions interact with fiscal policy, financial regulation, global markets, productivity, and private-sector behavior. A credible central bank can help create stable monetary and financial conditions, but lasting economic performance depends on institutions and policies far beyond the central bank itself.
Comments 0
No comments yet. Be the first to start the conversation.